
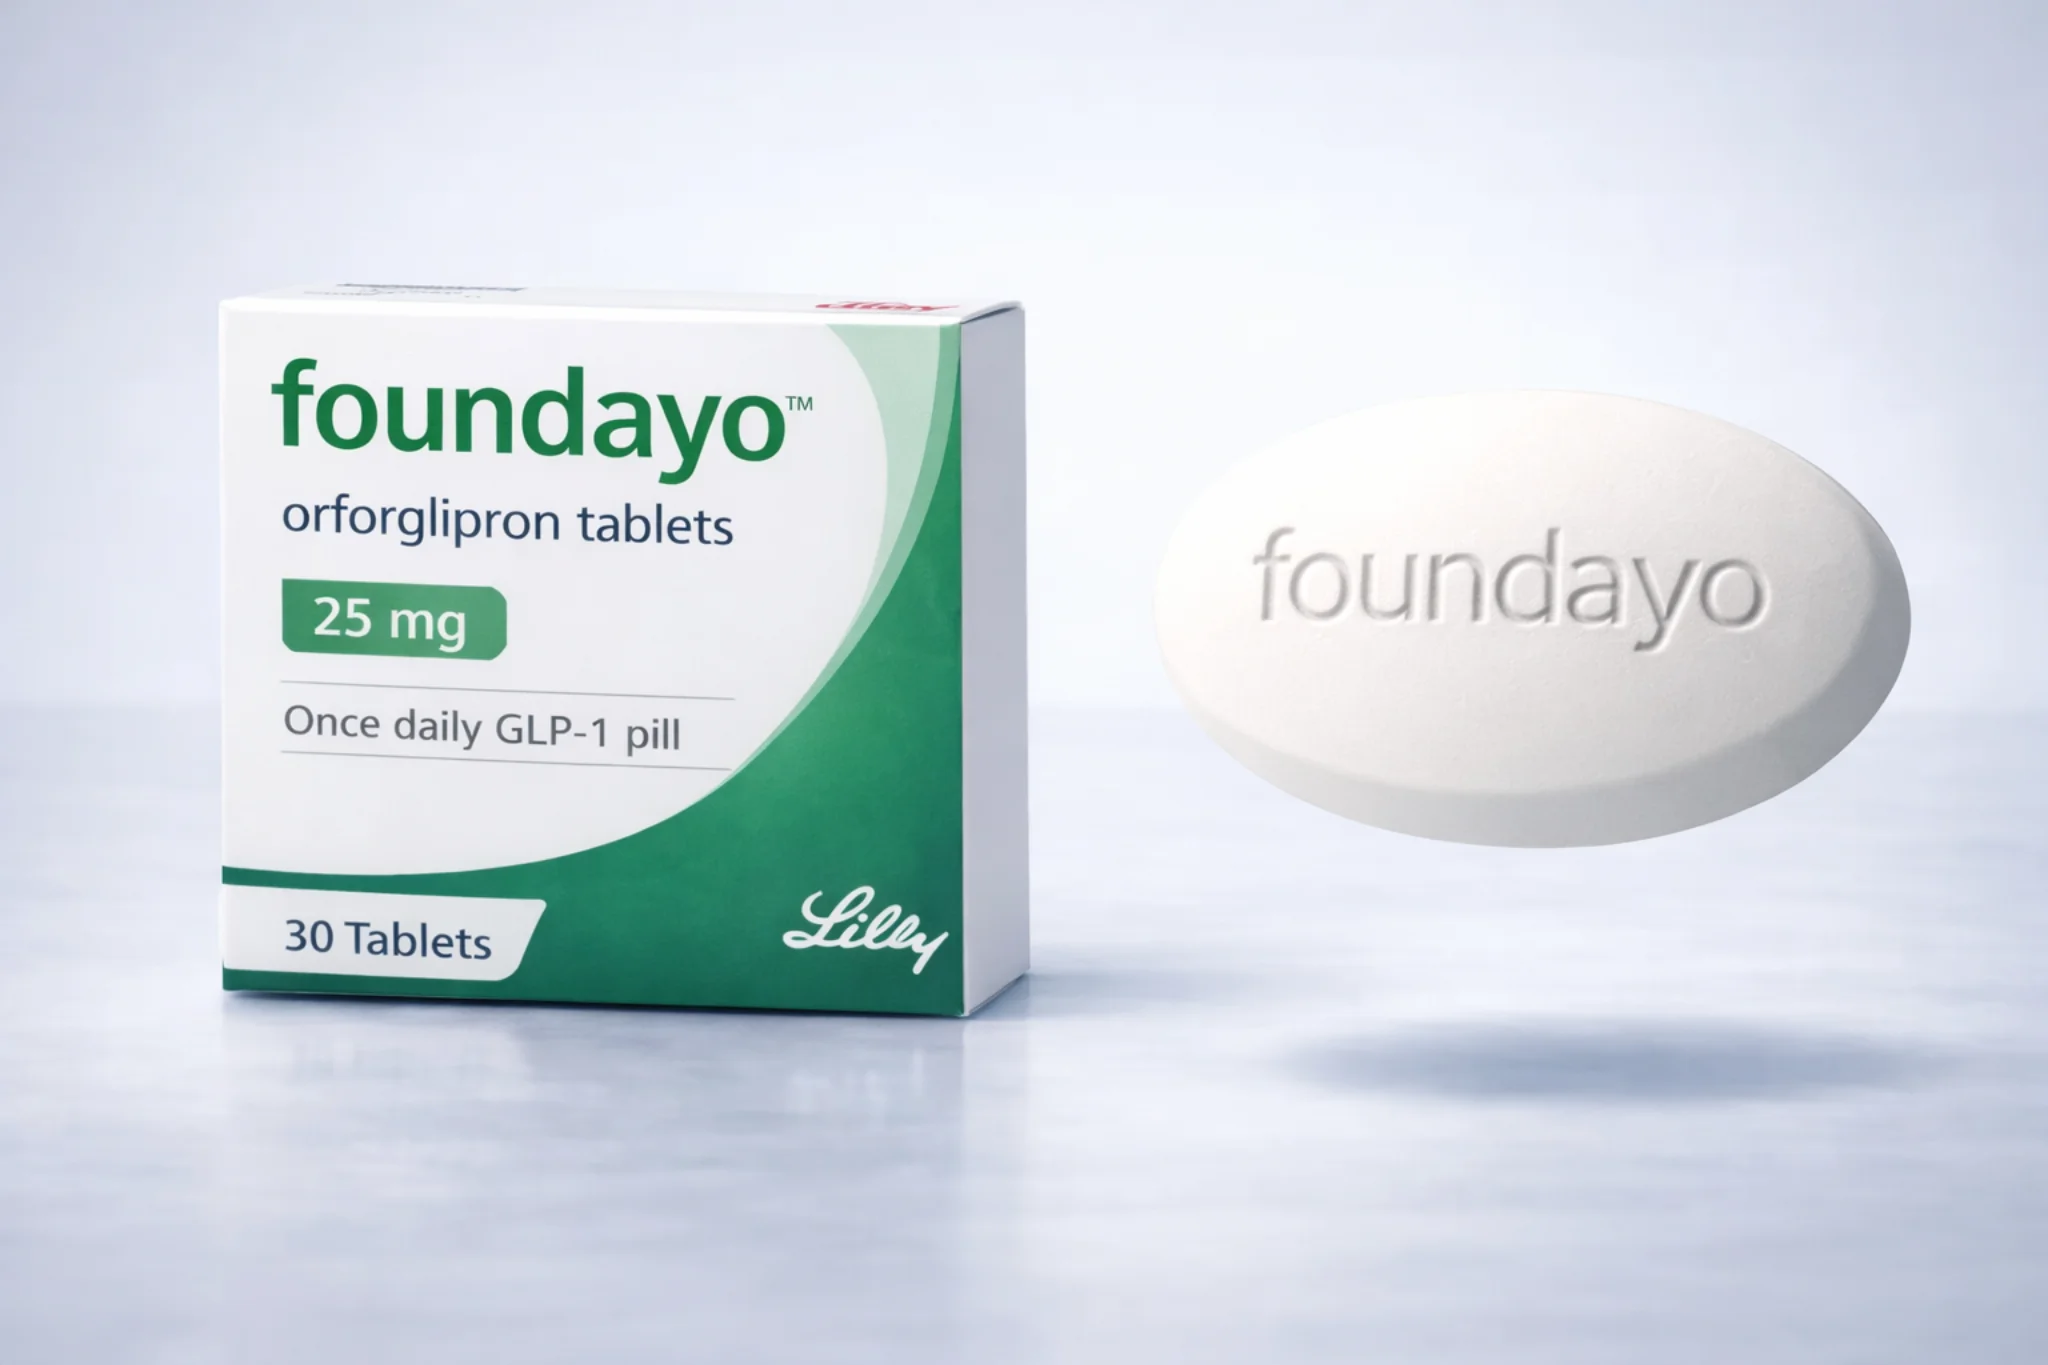
Short answer: This interactive checklist tracks everything you need for Foundayo prior authorization—weight records, health condition documentation, proof of diet/exercise attempts, and insurance forms. Check items as you gather them; progress saves in your browser.
What documents do I need for Foundayo prior authorization?
Most insurers require documentation in three categories:
- Weight records showing you meet eligibility (BMI 30+, or BMI 27+ with a weight-related health condition)
- 6 months of diet and exercise attempts
- Any previous weight loss medications you've tried
Who this checklist is for
Patients preparing for Foundayo prior authorization, or those who were denied and need to gather additional documentation for appeal.
Your GLP-1 coverage,
denied approved
✓ Free Templates✓ Premium Support Available
I was denied coverage for...
Get starteddenied approved
Honest Care helps patients fight back:
Evidence-backed appeal letters — plus personalized guidance to appeal with confidence.
"I found Honest Care online and was very impressed with the letter... the appeal worked!"
"My Appeal was approved the next day. Thank you Honest Care!"
TRACK YOUR PROGRESS
Your Foundayo PA Checklist
Use This Interactive Checklist
Check off items as you gather them. Your progress is saved in your browser. When you're done, download the checklist to share with your doctor.
0 of 12 items complete (0%)
Before Your Appointment
Documentation to Gather
After Submission
WHAT INSURERS REQUIRE
Documents to Gather
Every insurer has slightly different requirements, but most will ask for these core documents. Gather them before your doctor's appointment to avoid delays.
What is Prior Authorization?
Prior authorization (PA) is when your insurance requires your doctor to get approval before they'll cover a medication. It's their way of checking that the treatment is medically necessary for your situation.
BMI and Weight Documentation
BMI (Body Mass Index) is a number calculated from your height and weight. Your doctor can calculate this for you.
- Current BMI measurement — Should be recent (from a current office visit)
- Weight history — At least 1-2 years of documented weights showing your pattern
- Height measurement — For BMI calculation verification
Requirement
BMI ≥30 or BMI ≥27 with at least one weight-related health condition (high blood pressure, type 2 diabetes, sleep apnea, etc.)
*Some insurers like BCBS have stricter requirements (BMI ≥35). Always verify with your specific plan.
Weight-Related Health Conditions
If your BMI is 27-29.9, you'll need documented proof of at least one weight-related health condition:
| Condition | Medical Code | What You Need |
|---|---|---|
| Type 2 Diabetes | E11.x | A1C blood test results, diagnosis date |
| High Blood Pressure | I10 | Blood pressure readings, medication list |
| Sleep Apnea | G47.33 | Sleep study results |
| High Cholesterol | E78.5 | Cholesterol test results |
| Polycystic Ovary Syndrome (PCOS) | E28.2 | Diagnosis, hormone test results |
Note: The medical codes (ICD-10) are for your doctor—you don't need to know them. Just make sure your conditions are documented in your medical records.
Prior Weight Loss Attempts
Most insurers require proof you've tried to lose weight before requesting medication. Document:
- Diet programs — Dates, type (low-calorie, keto, etc.), outcomes
- Exercise regimens — Duration, frequency, results
- Previous medications — Drug name, dosage, dates, why discontinued
- Bariatric surgery consideration — If applicable, why not pursued
What is "Step Therapy"?
Step therapy means your insurer wants you to try a cheaper medication first before approving Foundayo. Common requirements include trying medications like Qsymia, Contrave, or other anti-obesity drugs for 3+ months. If you've already tried other weight loss medications, gather those records—it may satisfy this requirement.
Lab Results (Blood Tests)
Have these blood test results ready (from within the last 3-6 months):
- A1C — Measures average blood sugar over 3 months (shows diabetes/prediabetes)
- TSH — Thyroid test to rule out thyroid problems causing weight gain
- Lipid panel — Checks cholesterol and triglycerides
- Liver function tests — Checks liver health (some insurers require this)
Don't have recent labs? Your doctor can order these at your appointment.
Insurance Information
- Member ID — From your insurance card
- Group number — If applicable
- Plan name — Specific plan type (PPO, HMO, etc.)
- Pharmacy benefit contact — Often different from medical benefits
- Prior authorization phone/fax — For your doctor's office
PREPARE FOR YOUR APPOINTMENT
Information Your Doctor Needs
Come to your appointment prepared with this information so your doctor can complete the PA form accurately:
Weight History
- Your highest adult weight
- Current weight
- Past 1-2 years of weights (if available)
- Any significant weight changes
Medication History
- Previous weight loss medications tried
- Dosages and duration
- Why you stopped (side effects, cost, didn't work)
- Current medications
Diet & Exercise History
- Structured programs (Weight Watchers, Noom, etc.)
- Dates and duration
- Results achieved
- Current exercise routine
Health Conditions
- All diagnosed conditions
- When diagnosed
- Current treatments
- Impact on daily life
Pro Tip
Bring a written summary of this information to your appointment. It helps your doctor fill out the PA form completely and reduces back-and-forth with your insurance.
CALL BEFORE YOUR APPOINTMENT
Questions to Ask Your Insurance
Call your insurance before your doctor's appointment to understand exactly what they require. Use this call script:
Opening:
"Hi, I'm calling to check coverage for a medication called Foundayo (orforglipron) for chronic weight management. I'd like to understand the prior authorization requirements."
Essential Questions
"Is Foundayo on my plan's formulary?"
A "formulary" is your insurance's list of covered medications. If Foundayo isn't on it, ask about alternatives or requesting an exception.
"What are the exact prior authorization criteria?"
Ask them to email or mail you the specific requirements document.
"Is there a step therapy requirement?"
Ask which medications you must try first and for how long.
"What BMI is required? Do I need documented health conditions?"
Get the specific weight and health condition requirements in writing.
"What documentation is required for approval?"
Ask about specific forms, lab requirements, and chart notes.
"How long is the authorization valid once approved?"
Typical duration is 6-12 months before renewal.
"If denied, what is the appeal process?"
Note deadlines and what additional information may help.
Document Everything
Write down the representative's name, date, time, and reference number. This protects you if there are disputes later.
WHY PAs GET DENIED
Common Mistakes to Avoid
These documentation errors cause the most preventable denials:
❌ BMI not recently documented
The fix: Schedule a quick vitals check if your last recorded weight is from months ago. Insurers want to see a current BMI from a recent office visit. Many offices can do this without a full appointment.
❌ Health conditions not properly coded
The fix: Ask your doctor to include specific medical diagnosis codes (called ICD-10 codes) for your conditions. Vague descriptions like "overweight" are often rejected. Your doctor knows which codes to use—just make sure all your weight-related conditions are documented.
❌ No documented prior weight loss attempts
The fix: Even if not in your medical record, tell your doctor about diets, exercise programs, and weight loss medications you've tried. They can document your verbal history in chart notes.
❌ Step therapy not completed
The fix: If your insurer requires trying another medication first, document why it's not appropriate (contraindications, side effects, or prior failure). Your doctor can request a step therapy exception.
❌ Using outdated or wrong PA form
The fix: Ask your insurer for their current PA form. Forms change frequently—an outdated form may be auto-rejected.
❌ Not checking if Foundayo is covered first
The fix: Call your pharmacy benefits (this is often a different number than your regular insurance) before your doctor submits the PA. If Foundayo isn't on your plan's covered medication list, you may need to request an exception or explore self-pay options.
denied approved
Honest Care helps patients fight back:
Evidence-backed appeal letters — plus personalized guidance to appeal with confidence.
SHARE WITH YOUR DOCTOR
Download the Checklist
Foundayo PA Checklist (Printable PDF)
Get a printable version of this checklist to bring to your doctor's appointment or share with your healthcare team.
- All documentation requirements
- Questions for your insurance
- Information your doctor needs
- Common mistakes to avoid
Use your browser's print function to save as PDF
PREPARE NOW
What's Changing in 2026
Coverage Policies Are Still Forming
Foundayo was FDA-approved on April 1, 2026. Insurers are still establishing coverage policies, which means requirements vary widely. Gather comprehensive documentation now to be prepared for any PA criteria your insurer requires.
Key 2026 Changes to Know
No Grandfathering of Existing PAs
Some insurers have announced no grandfathering of existing GLP-1 PAs at plan renewals in 2026. Even if you're currently approved, you may need to resubmit documentation under new criteria when your plan renews.
TrumpRx: No PA Needed
The TrumpRx program launched February 5, 2026 and lists Foundayo at LillyDirect’s own self-pay prices—$149/month for the starting dose (0.8mg), $149 for the 2.5mg dose (temporary price through December 31, 2026), up to $299 for higher doses; orders go through LillyDirect. No PA, no step therapy, no documentation required. (Medicare’s $50/month price is a separate program, the Medicare GLP-1 Bridge, below.)[11]
Medicare GLP-1 Bridge: live now
Foundayo is covered by the Medicare GLP-1 Bridge (July 1, 2026 – December 31, 2027) for $50 per monthly fill, if you have Part D coverage and meet CMS’s eligibility criteria. The Bridge has its own PA: After the pharmacy sends the claim, your prescriber completes the Bridge prior authorization; the decision comes within 72 hours of submission, mailed to you and sent to your prescriber (through the ePA portal or by fax). The BALANCE model in Medicare Part D is Delayed, with no new start date.
2026 Checklist Additions
- Verify coverage with your specific plan: Foundayo is new—don't assume coverage without checking
- Document everything now: Complete medical records support initial PA and future appeals
- Know your self-pay backup: LillyDirect offers Foundayo at $149–$299/month without insurance
- Check TrumpRx: No-PA option at the same LillyDirect prices, starting at $149/month
PA CHECKLIST QUESTIONS
Frequently Asked Questions
For most employer and ACA plans, federal rules require a decision within 15 days (one 15-day extension allowed), and many plans decide sooner; urgent requests must be decided within 72 hours. If you haven't heard back in a week, call to follow up.
Tell your doctor about any diets, exercise programs, or weight loss medications you've tried—even without formal documentation. They can record your verbal history in chart notes, which counts as documentation for most insurers.
Many insurers have step therapy requirements, meaning you must try other medications first (like Qsymia, Contrave, or other anti-obesity drugs). However, your doctor can request an exception if these aren't right for you—for example, if you have a medical reason you can't take them, or if you've already tried them without success.
The FDA approved Foundayo for people with BMI 30 or higher, or BMI 27+ with at least one weight-related health condition (like type 2 diabetes, high blood pressure, or sleep apnea). Some insurers have stricter requirements, so check your specific plan.
You have the right to appeal. Most patients have 180 days to file an appeal for commercial insurance. Request the denial reason in writing and gather additional documentation. Learn how to appeal a denial.
Some insurance plans don't require prior authorization, but most do. You can also use LillyDirect to pay out-of-pocket without insurance approval—starting at $149/month through the manufacturer.
YOUR PATH FORWARD
What's Next
References
- Eli Lilly and Company. (April 1, 2026). "FDA approves Lilly's Foundayo (orforglipron), the only GLP-1 pill for weight loss that can be taken any time of day without food or water restrictions." Press release. investor.lilly.com
- U.S. Food and Drug Administration. (2026). "Foundayo (orforglipron) Prescribing Information." FDA-approved April 1, 2026. Drugs@FDA
- HealthCare.gov. "Prior Authorization - Glossary." healthcare.gov
- American Medical Association. (2024). "Prior Authorization and Utilization Management Reform Principles." ama-assn.org
- Kaiser Family Foundation. (2024). "Claims Denials and Appeals in ACA Marketplace Plans." kff.org
- Eli Lilly and Company. (2025). "Lilly's orforglipron Phase 3 ATTAIN-1 results." Clinical trial results presented and published via Lilly investor relations. investor.lilly.com
- U.S. Food and Drug Administration. (April 1, 2026). "FDA Approves Foundayo (orforglipron) for Chronic Weight Management." fda.gov
- American Association of Clinical Endocrinology. (2023). "Clinical Practice Guideline for the Diagnosis and Management of Obesity." aace.com
- Centers for Medicare & Medicaid Services. (2024). "CMS-0057-F: Interoperability and Prior Authorization Final Rule." cms.gov
- Eli Lilly and Company. "Foundayo (orforglipron) Official Site." foundayo.lilly.com
- CBS News. (April 2, 2026). "Foundayo becomes latest GLP-1 drug available through TrumpRx program." Foundayo listed on TrumpRx at LillyDirect’s self-pay prices. cbsnews.com
Last updated October 6, 2026
Disclaimer
The information on this page is for educational and informational purposes only and is not intended as medical advice. Honest Care does not provide medical diagnosis, treatment, or individualized recommendations. Always seek the advice of your physician or other qualified healthcare professional regarding any medical condition or treatment.
While this content has been reviewed for accuracy and balance, new evidence may emerge after publication. Drug availability, indications, and insurance coverage can change over time. Honest Care makes no warranties as to completeness or currentness of the information and is not responsible for decisions made based on this content.